Build-to-Rent Growth and Its Impact on Housing Markets
The build-to-rent sector has emerged as one of the most consequential forces reshaping residential property markets, channeling institutional capital into purpose-built rental communities at a pace that is fundamentally altering the balance between homeownership and tenancy across major metropolitan areas. As developers increasingly pivot from for-sale housing to meet surging demand from renters priced out of ownership, the long-term implications for housing affordability, neighbourhood composition and the broader socioeconomic contract around property wealth remain deeply contested among policymakers and market participants alike.…
Build-to-Rent Growth and Its Impact on Housing Markets
The global build-to-rent sector has crossed a threshold that even its most ardent proponents did not anticipate five years ago. Institutional capital committed to purpose-built rental housing surpassed $180 billion globally in the first quarter of 2026, according to JLL's latest capital flows tracker, with the Gulf Cooperation Council states and select emerging markets absorbing an increasingly outsized share of that investment. What started as a niche strategy pioneered by American multifamily operators and British housing associations has become one of the most contested asset classes in international real estate — and it is fundamentally reshaping how housing markets function.
The Gulf's Institutional Pivot to Rental Housing
Abu Dhabi's Aldar Properties reported in February 2026 that its build-to-rent portfolio had grown to approximately 9,400 units across the emirate, with a further 3,200 units under construction in the Saadiyat Island and Yas Island corridors. Rental revenue climbed 28 per cent year-on-year, outpacing its sales-led residential division for the first time. That is a significant shift. CEO Talal Al Dhiyebi called it "structural, not cyclical," pointing to the UAE's expanding expatriate workforce and revised long-term visa frameworks as demand anchors that traditional for-sale housing cannot adequately serve.
Dubai's DIFC-based developer Arada announced a $1.2 billion dedicated rental fund in January, backed by a consortium that includes a prominent Kuwaiti family office and Saudi Arabia's Hassana Investment Company, the asset management arm of the General Organisation for Social Insurance. The fund targets 6,000 units across Sharjah's Aljada masterplan and a new Riyadh venture, with projected net yields of 6.8 to 7.4 per cent — comfortably above the 4.5 per cent cap rates now typical of stabilised European build-to-rent assets.
Saudi Arabia's own pipeline is staggering. The Kingdom's National Housing Company, operating under the Ministry of Municipal, Rural Affairs and Housing, has earmarked 42,000 rental units across Riyadh, Jeddah, and NEOM's Oxagon district as part of its Vision 2030 housing targets. Roshn, the PIF-backed real estate developer, confirmed in March that 15 per cent of its total residential output would be designated for institutional rental. That marks a clear departure from its original sales-only model.
Family Offices and Private Wealth Reshape Capital Structures
Dig beneath those headline figures and the most striking capital shift becomes visible: Gulf and Asian family offices are entering build-to-rent as direct operators, not passive limited partners. The Olayan Group, one of Saudi Arabia's most established family conglomerates, has assembled a dedicated real estate team in Riyadh to manage a 2,800-unit rental portfolio it acquired from a distressed regional developer in late 2025. The Al Futtaim family's investment arm in Dubai has similarly pivoted, committing $640 million to a joint venture with Greystar Real Estate Partners to develop mid-market rental communities in Dubai South and Al Furjan.
This trend extends well beyond the Gulf. Few outside the region have noticed. Singapore-based family office Domus Capital, backed by Indonesian timber and palm oil wealth, deployed $310 million across build-to-rent projects in Ho Chi Minh City and Bangkok during 2025, targeting the expanding middle-class renter demographic in Southeast Asia. In India, the Godrej family's real estate arm has partnered with Brookfield Asset Management to develop 4,500 rental apartments in Mumbai's Bandra-Kurla Complex and Bengaluru's Whitefield technology corridor, with first deliveries expected by Q3 2026.
These family offices bring patient capital and a tolerance for compressed early yields that institutional funds frequently cannot match. Knight Frank's 2026 Wealth Report found that 34 per cent of ultra-high-net-worth individuals surveyed across the Middle East and Asia now hold build-to-rent assets directly, up from just 11 per cent in 2022. Triple in four years.
Impact on Housing Affordability and Market Dynamics
The proliferation of institutional rental stock is producing measurable effects on housing markets, though the outcomes are neither uniformly positive nor straightforward. In Dubai, where roughly 14,000 build-to-rent units were delivered in 2025 alone, CBRE data shows that rental growth in professionally managed developments moderated to 4.2 per cent annually, compared with 11.6 per cent in the fragmented individual-landlord segment. The implication is hard to miss: institutional supply is exerting a disciplining effect on rental inflation, at least at the mid-to-upper price tiers where most build-to-rent product sits.
But critics have a point. That supply discipline does not reach the segments of the market where affordability pressures bite hardest. Research published by the Oxford Economics housing unit in March 2026 found that fewer than 18 per cent of build-to-rent units delivered globally in 2025 targeted households earning below the median income in their respective cities. The bulk of new stock caters to young professionals, corporate relocations, and digital nomads — demographics with relatively elastic housing budgets.
In Riyadh, where population growth is running at approximately 3.5 per cent annually driven by Vision 2030 employment targets, the construction of institutional rental units has coincided with a 22 per cent increase in land values across the northern expansion zones. Local developers report that build-to-rent projects are competing directly with affordable for-sale housing for entitled land parcels, driving up input costs across the board. So the sector that was supposed to ease housing pressure may, in some corridors, be making it worse.
Regulatory Frameworks Struggle to Keep Pace
Governments across the Gulf and emerging markets are wrestling with how to regulate an asset class that sits uncomfortably between traditional real estate and financial services. The UAE's Real Estate Regulatory Agency introduced new build-to-rent licensing requirements in January 2026, mandating minimum lease terms of 12 months and capping annual rent increases at 5 per cent for institutional landlords with portfolios exceeding 500 units. Tenant advocacy groups welcomed the regulation. Operators did not — they argued it would suppress new investment at precisely the moment more supply was needed.
Saudi Arabia's Capital Market Authority is meanwhile developing a framework to allow build-to-rent portfolios to be packaged into listed REITs, following the model established by the United Kingdom's regulatory approach. Riyad Capital and SNB Capital are both understood to be structuring inaugural build-to-rent REIT offerings for launch in late 2026, which would give retail investors their first direct exposure to the sector in the Kingdom.
In India, the regulatory picture remains fragmented. The Maharashtra Real Estate Regulatory Authority has proposed treating build-to-rent developments as a distinct category under RERA, with separate disclosure and escrow requirements. The proposal has stalled amid lobbying from developers who prefer the existing framework's flexibility. No one expects a resolution soon.
The Road Ahead: Maturation, Not Saturation
For all the capital pouring into build-to-rent, the sector remains in early-stage development across most emerging markets. Consider the numbers. Institutional rental housing represents less than 3 per cent of total housing stock in the UAE, under 1 per cent in Saudi Arabia, and a negligible fraction in India and Southeast Asia. By contrast, it accounts for roughly 7 per cent in the United Kingdom and 12 per cent in the United States.
The growth trajectory is clear, but so are the risks. Rising construction costs, regulatory uncertainty, and the potential for oversupply in specific submarkets — Dubai Marina and Business Bay among them — will test the conviction of investors who entered the sector during a period of compressed yields and abundant liquidity. Family offices with generational time horizons may prove better positioned than institutional funds facing quarterly redemption pressures.
What is no longer debatable is that build-to-rent has moved from the periphery to the centre of global housing strategy. The question confronting policymakers and investors alike is whether the sector can deliver the volume, affordability, and quality that rapidly urbanising populations across the Gulf and emerging world urgently require — or whether it will remain, for all its growth, a premium product serving a narrow band of the income spectrum.
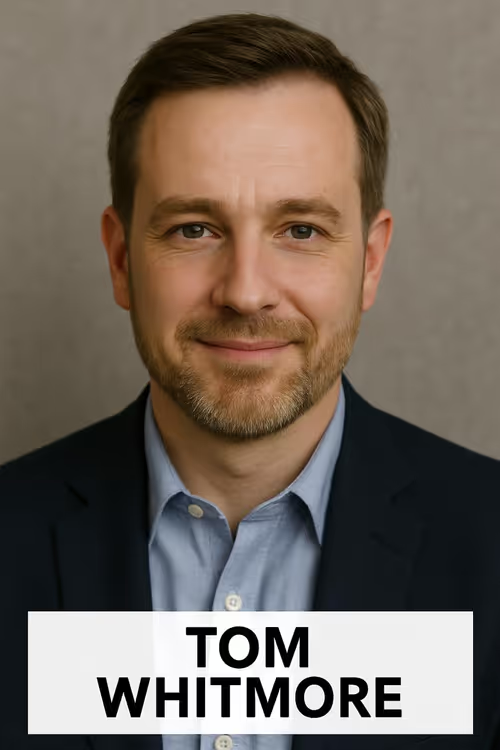
Written by
Tom Whitmore
Senior correspondent · Real Estate & Private Companies
Tom has interviewed most of the operators reshaping the Gulf skyline — and a few of the ones who tried and didn't. His beat is real estate, commodities, manufacturing, and the founder-led private companies that never bother to list. He knows which buildings and balance sheets survive a downturn before the spreadsheet does. Based in Dubai. Reach out at tom.whitmore@theplatinumcapital.com.